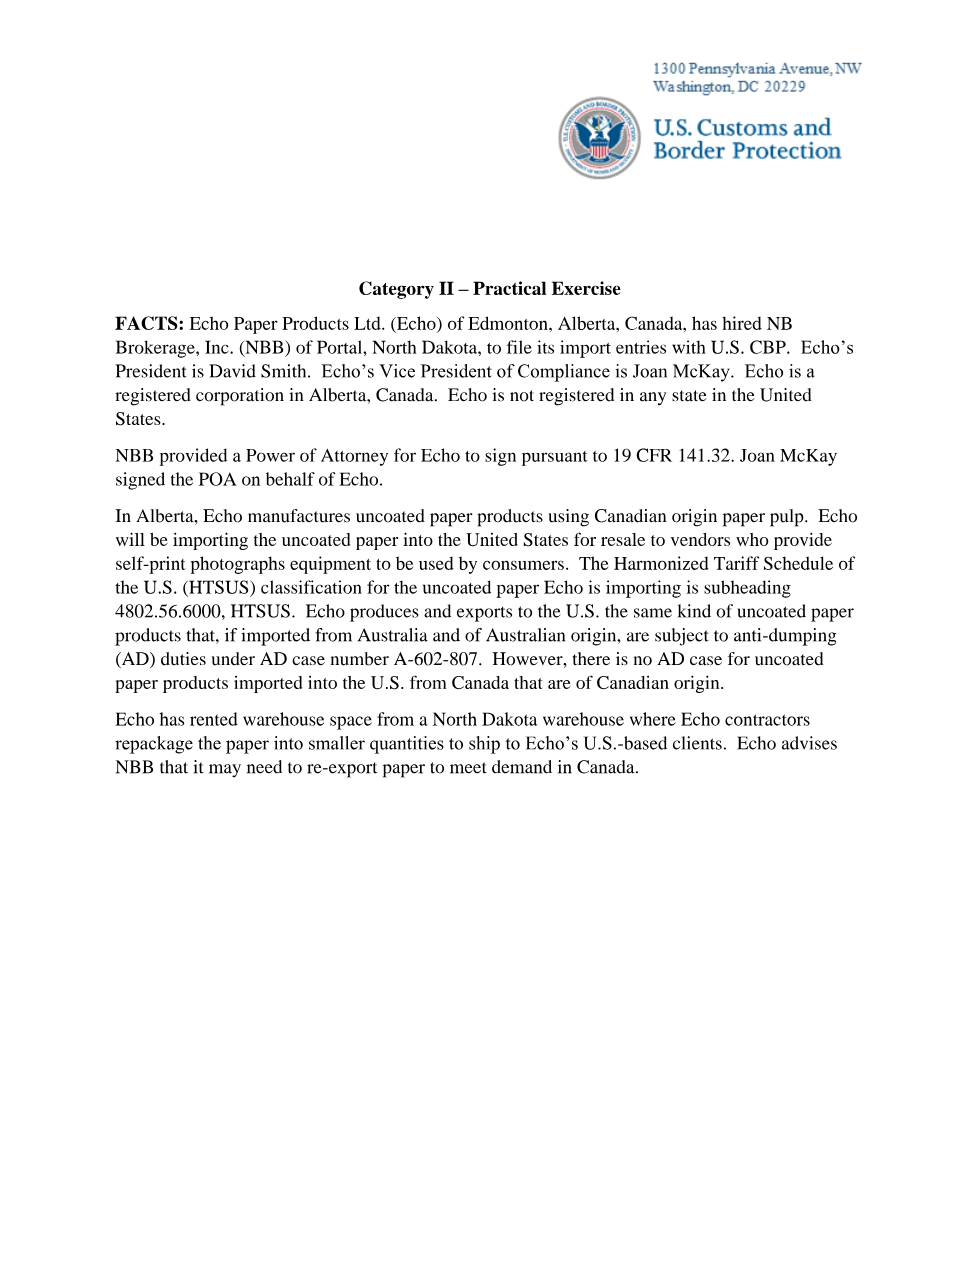
NBB determines it needs to make a USMCA post-summary claim on a type 01 consumption entry filed on behalf of Echo. Of the following methods for making post-summary claims, which ONE cannot be used to make a post-summary claim under the USMCA?
How to get there
19 CFR 182.31… where a good would have qualified as an originating good when it was imported … but no claim for preferential tariff treatment was made, the importer … may file a claim for a refund of any excess customs duties at any time within one year after the date of importation … in accordance with 19 U.S.C. 1520(d) …
ACE BRPD § 6.5: In-Eligible ChangesData elements that cannot be changed for any entry type: … • USMCA Indicator 19 U.S.C § 1520(d) indicator … The filer may not submit a PSC to amend an entry summary for Trade Preference Programs covered under 19 USC 1520(d).
A post-summary correction can't add the USMCA claim. The answer is B.
Why the other choices are wrong
A) A 1520(d) post-importation claim: the main route, within one year of importation (§ 182.31).
C) FTA reconciliation: available if the entry was flagged for FTA reconciliation at filing.
D) Protest after liquidation: a protest can challenge the liquidation's rate of duty (§ 174.11(b)(2)), including the refusal to reliquidate under 1520(d) (§ 174.11(b)(8)).
Tip
FTA claim missed at entry? Use a 1520(d) claim (1 year from importation), FTA reconciliation (if flagged), or a protest. Not a PSC: ACE blocks 1520(d) indicators on PSCs.
Sources: 19 CFR 182.31, 174.11; CBP ACE BRPD § 6.5 (Post Summary Corrections, In-Eligible Changes).
CBP answer key: Answer B · ACE BRPD Chapter 6, Section 6.5; ACE BRPD Chapter 10; 19 CFR 182.31; 19 CFR 174.11Source: CBP past exams ↗