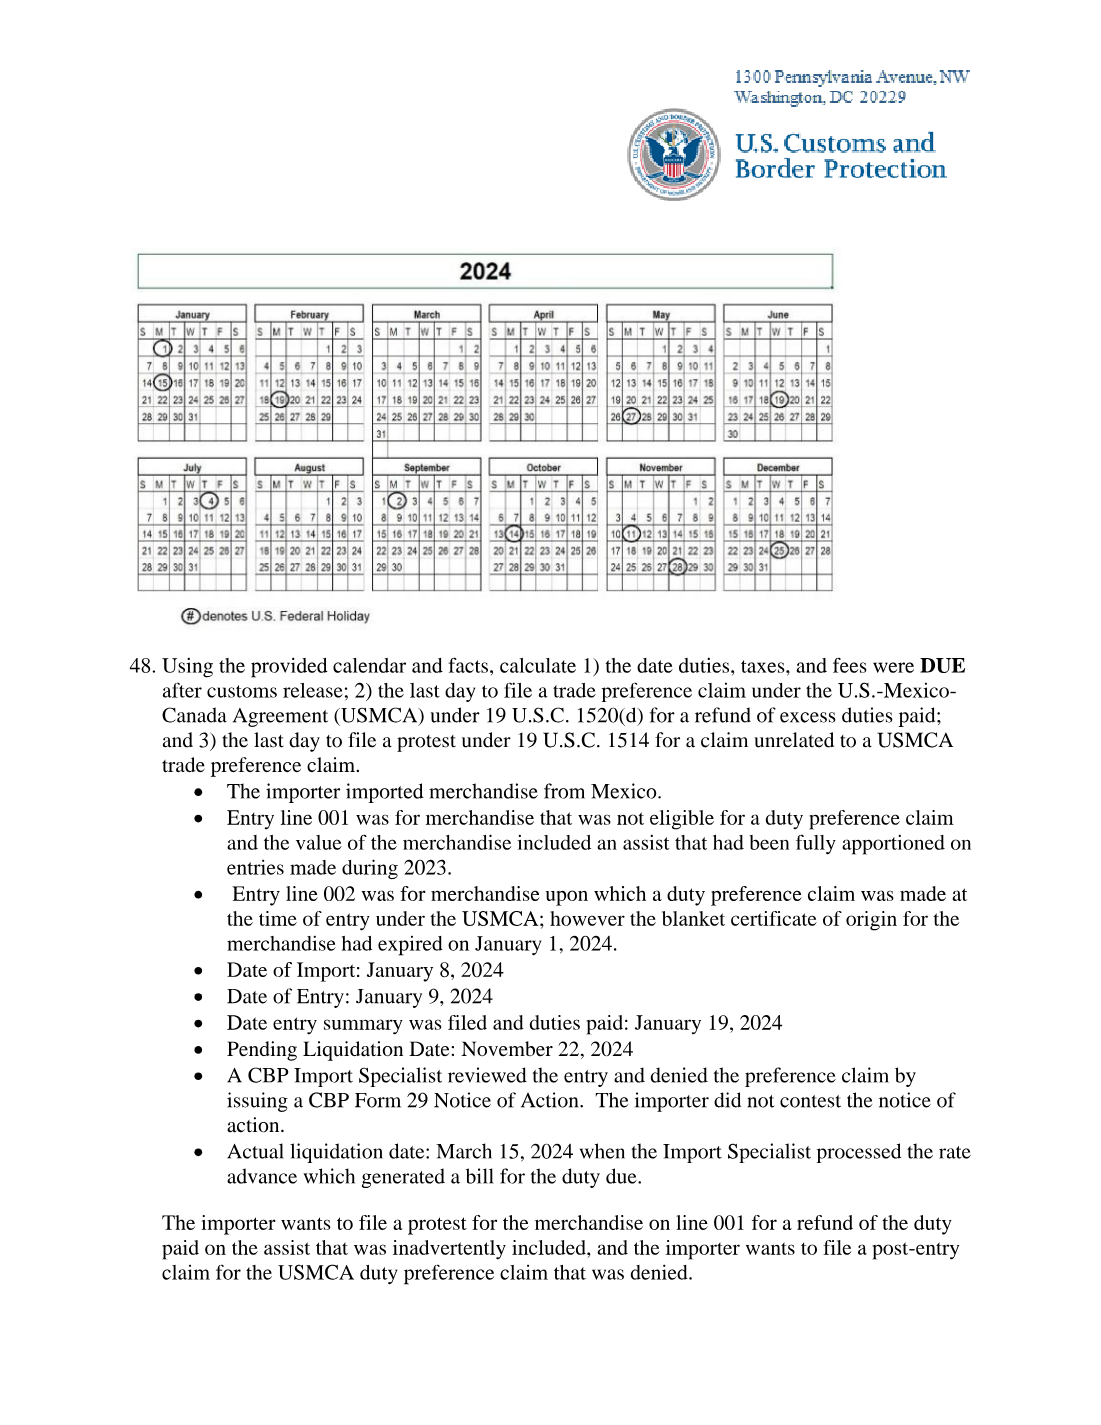
Using the provided calendar and facts, calculate 1) the date duties, taxes, and fees were DUE after customs release; 2) the last day to file a trade preference claim under the U.S.-Mexico- Canada Agreement (USMCA) under 19 U.S.C. 1520(d) for a refund of excess duties paid; and 3) the last day to file a protest under 19 U.S.C. 1514 for a claim unrelated to a USMCA trade preference claim. • The importer imported merchandise from Mexico. • Entry line 001 was for merchandise that was not eligible for a duty preference claim and the value of the merchandise included an assist that had been fully apportioned on entries made during 2023. • Entry line 002 was for merchandise upon which a duty preference claim was made at the time of entry under the USMCA; however the blanket certificate of origin for the merchandise had expired on January 1, 2024. • Date of Import: January 8, 2024 • Date of Entry: January 9, 2024 • Date entry summary was filed and duties paid: January 19, 2024 • Pending Liquidation Date: November 22, 2024 • A CBP Import Specialist reviewed the entry and denied the preference claim by issuing a CBP Form 29 Notice of Action. The importer did not contest the notice of action. • Actual liquidation date: March 15, 2024 when the Import Specialist processed the rate advance which generated a bill for the duty due. The importer wants to file a protest for the merchandise on line 001 for a refund of the duty paid on the assist that was inadvertently included, and the importer wants to file a post-entry claim for the USMCA duty preference claim that was denied.
Full explanation locked
The worked reasoning, quoted regulation text and wrong-option analysis for this question are part of the CBLE Pass or the single-exam unlock.
See options → Already bought? Sign in